December 20, 2021
If you’re a homeowner who’s decided your current house no longer fits your needs, or a renter with a strong desire to become a homeowner, you may be hoping that waiting until next year could mean better market conditions to purchase a home.
To determine whether you should buy now or wait another year, you can ask yourself two simple questions:
Where will home prices be a year from now?
Let’s shed some light on the answers to both of these questions.
Three major housing industry entities are projecting ongoing home price appreciation in 2022. Here are their forecasts:
Fannie Mae: 7.4%
Freddie Mac: 7%
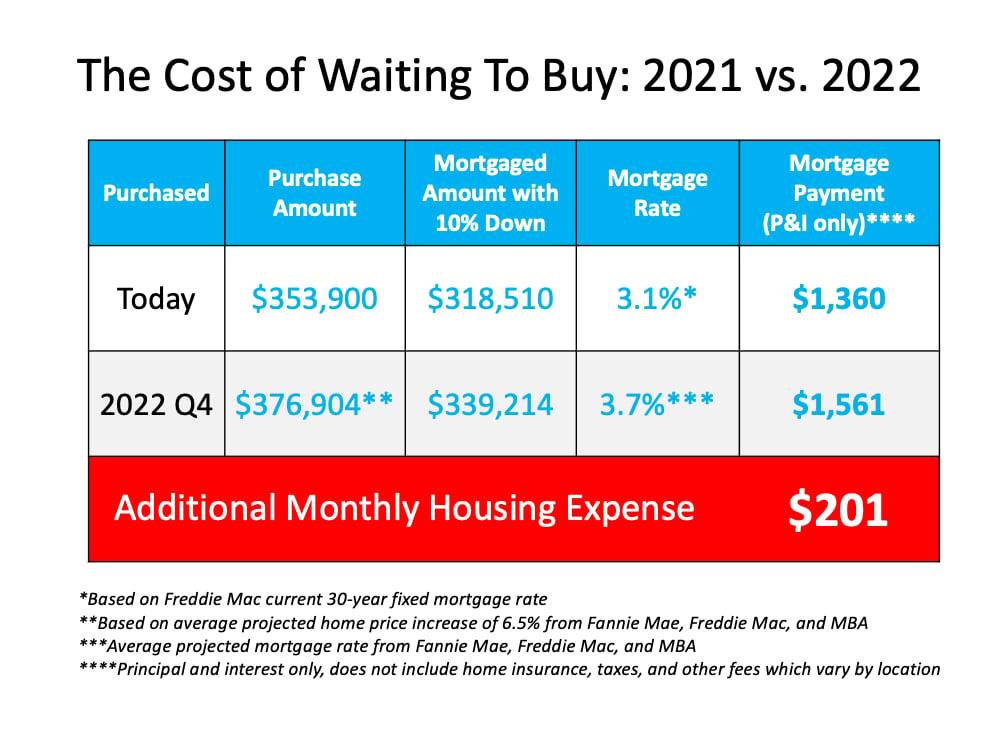
According to the National Association of Realtors (NAR), the median price of a home today is $353,900. Using an average of the three price projections above (6.5%), a home that sold for $353,900 today would be valued at $376,904 at the end of next year. As a prospective buyer, you would therefore pay an additional $23,004 by waiting.
Today, Freddie Mac announced their 30-year fixed mortgage rate was at 3.1%. However, most experts believe mortgage rates will rise as the economy recovers. Here are the forecasts for the fourth quarter of 2022 by the three major entities mentioned above:
Fannie Mae: 3.4%
Freddie Mac: 3.7%
That averages out to 3.7% if you include all three forecasts. Any increase in mortgage rates will increase your costs.
If both variables increase, you’ll pay a lot more in mortgage payments each month. Let’s assume you purchase a $353,900 home today with a 30-year fixed-rate loan at 3.1% (the current rate from Freddie Mac) after making a 10% down payment. According to mortgagecalculator, your monthly mortgage payment would be approximately $1,360 (this does not include insurance, taxes, and other fees because those vary by location).
That same home one year from now could cost $376,904, and the mortgage rate could be 3.7% (based on the industry forecasts mentioned above). Your monthly mortgage payment after putting down 10%, would be approximately $1,561.
The difference in your monthly mortgage payment would be $201. That’s $2,412 more per year and $72,360 over the life of the loan.
Add to that the approximately $23,004 a house with a similar value would build in home equity this year due to home price appreciation, and the total net worth increase you could gain by buying this year is over $95,364 (the $72,360 mortgage savings plus the $23,004 potential gain in equity if you buy now).
When asking if you should buy a home, you may think of the non-financial benefits of homeownership. When asking when to buy, the financial benefits make it clear that doing so now is much more advantageous than waiting until next year.
Stay up to date on the latest real estate trends.
Leading with our core standards and values we approach every decision with honesty and integrity. We take great responsibility in doing the right thing because it is the right thing to do.